 comparison
Arizona Insurance Brokers vs Direct Carriers: Which Is Better?
Last Updated: October 28, 2026
Quick Summary
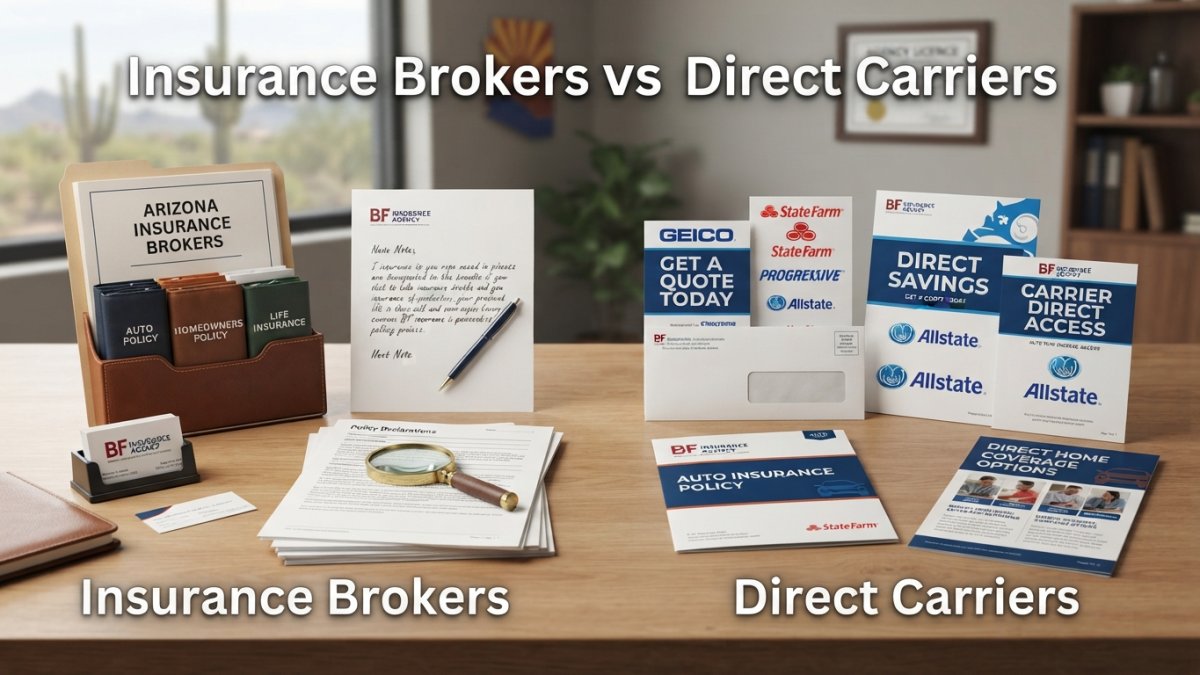
The difference in insurance brokers vs direct carriers is structural: a broker can place your policy with many insurance companies, while a direct carrier sells only its own products. Neither model is universally better; the right choice depends on how complex your coverage needs are and how much help you want after the policy is issued.
- Brokers typically earn a commission paid by the carrier, so broker services often cost the customer nothing extra.
- Compare quotes by matching coverage limits, deductibles, and exclusions before you look at price.
- Bundling is not automatically cheaper; two separate policies can beat a bundle even after the credit is removed.
- A direct carrier may suit someone with straightforward coverage needs who prefers handling insurance online.
- Ask a broker how many carriers they represent, how they are compensated, and whether they re-shop at renewal.
Table of Contents
- Arizona Insurance Brokers vs Direct Carriers: What Is the Difference?
- How Brokers and Direct Carriers Make Money
- How to Compare Insurance Quotes Step by Step
- Questions to Ask an Insurance Broker Before You Commit
- Home and Auto Insurance Bundle Comparison: Broker vs Direct
- When a Direct Carrier May Be the Better Choice
- Arizona Consumer Protections and Complaint Resources
- Get Started with a Personalized Arizona Insurance Quote
- Frequently Asked Questions
Arizona Insurance Brokers vs Direct Carriers: What Is the Difference?
Arizona insurance brokers vs direct carriers comes down to one structural fact: a broker can place your policy with many insurance companies, while a direct carrier sells only its own products. That single difference shapes everything else, from how quotes are gathered to who answers the phone when you file a claim.
Neither model is universally better. The right choice depends on how complex your coverage needs are and how much help you want after the policy is issued.
An insurance broker is a licensed intermediary who compares coverage options across multiple carriers and advises on which policy fits your situation. A direct carrier is an insurance company that sells its own policies through its own agents, website, or call center.
Below is an overview of how each model earns money, how to compare quotes fairly, and when going direct actually makes sense.
How Brokers and Direct Carriers Make Money
Brokers typically earn a commission paid by the carrier when a policy is placed, which is why broker services often cost the customer nothing extra. Direct carriers keep that distribution cost in-house instead. That one sentence hides most of what a shopper actually needs to know, so here is the mechanism in full.
How broker compensation works
A broker may be compensated in different ways. Ask how the broker is paid and whether any fees apply.
Ask whether any fee applies and what it covers.
How direct carrier compensation works
A direct carrier sells its own policies. The trade-off is that it can only present its own products.
The conflict-of-interest question, answered plainly
The models differ. A broker may offer access to multiple carriers, while a direct carrier sells its own products.
Questions that surface the compensation model
- Are you paid by commission, a fee, or both, and who pays it?
- Do you receive a different commission rate from different carriers for the same line?
- Will you show me quotes from more than one carrier in writing?
- Is there any fee I would pay you directly, and what does it cover?
- If I cancel mid-term, does any commission or fee get refunded or charged back?
Those questions can help you assess a broker's independence.
How to Compare Insurance Quotes Step by Step
Comparing insurance quotes fairly means matching coverage limits, deductibles, and exclusions before you look at price. A cheaper premium on thinner coverage is not a saving.
Here is a method to consider:
- Write down your current coverage limits, deductibles, and endorsements.
- Request quotes for identical limits from every source, broker and direct alike.
- Ask each source which discounts were applied and which you may still qualify for.
- Check the financial strength rating of every carrier quoted.
- Compare total annual cost, not monthly payment, including any fees.
- Confirm what happens at renewal: will the rate be re-shopped or auto-renewed?
Renewal practices can differ. Ask what happens to your policy at renewal.
Questions to Ask an Insurance Broker Before You Commit
Ask an insurance broker these questions before sharing your information: how many carriers do you represent, how are you compensated, and will you re-shop my policy at renewal? The answers can help you understand the broker's services and compensation.
Our short list:
- How many carriers can you quote for my home, auto, and life needs?
- Are you paid by commission, a fee, or both?
- Which carriers do you not represent, and why?
- Will you review my coverage annually or only at renewal?
- Who handles my claim: you, or the carrier directly?
For common questions, see frequently asked Arizona insurance questions.
Home and Auto Insurance Bundle Comparison: Broker vs Direct
Bundling home and auto insurance may affect total cost. The details depend on the policies and carriers involved. A direct carrier offers its own policies, while a broker may compare options across carriers.
Where the choice actually differs by product
- Auto: Coverage options and quotes can depend on the drivers, vehicles, and driving history involved.
- Home: Home insurance options can depend on the home's condition, claims history, and other details.
- Umbrella and excess liability: Umbrella coverage options and how they coordinate with other policies depend on the carriers and policies involved.
- Life and disability: Life insurance is a separate coverage line to consider alongside home and auto insurance.
The bundle comparison at a glance
| Factor | Independent Broker | Direct Carrier |
|---|---|---|
| Carriers available | Multiple, with appointments per line | One |
| Bundle pricing | Compared across carriers and structures | Single carrier's discount only |
| Multi-policy coordination | Can split auto and home across carriers and add umbrella | Must keep all lines with one carrier |
| Renewal handling | Re-shopped by request | Auto-renewed |
| Claims support | Broker can advocate with the adjuster | Carrier's own adjuster |
| Best for | Complex, changing, or multi-line needs | Simple, stable, single-carrier needs |
What the bundle discount actually is
Bundling may affect the total premium. Ask for the bundled and separate-policy costs so you can compare them. A broker may compare options across carriers, while a direct carrier offers its own policies.
When bundling is not the answer
Bundling is not automatically cheaper. If one carrier is strong on auto and another is strong on home for your specific home age and claims history, two separate policies can beat a bundle even after the credit is removed. The only way to know is to price both structures with identical limits and deductibles. That is the comparison a broker is built to run, and it is the one a direct carrier cannot run for you.
If you are weighing whether bundling is worth it at all, read our breakdown of whether bundling home and auto insurance saves money before you commit to either path.
When a Direct Carrier May Be the Better Choice
A direct carrier may suit someone who prefers handling insurance online and has straightforward coverage needs.
Some shoppers may prefer dealing directly with an insurer.
Coverage options for leased vehicles, older homes, mixed households, and life insurance needs depend on the policies and carriers involved.
Arizona Consumer Protections and Complaint Resources
Arizona residents have formal recourse if a broker or carrier treats them poorly. The state's insurance regulator handles licensing and consumer complaints, and its consumer resources explain your rights in plain terms.
Consider keeping your policy declarations page, written records of advice you receive, and the name and license number of anyone who sells you a policy. If a dispute arises, the Arizona Department of Insurance and Financial Institutions consumer resources explain how to file a complaint.
Coverage rules also vary by county and by carrier, particularly for health plans. If you are shopping health coverage alongside home and auto, check plan availability in your area before assuming a quoted plan is offered where you live. The federal HealthCare.gov plan comparison tools let you confirm which plans serve your county.
Get Started with a Personalized Arizona Insurance Quote
The broker-versus-direct decision may be easier once you see numbers side by side.
BF Insurance Agency offers Arizona residents tailored auto, home, and life insurance solutions, with personalized coverage and guidance. You can explore our insurance brokerage services in Arizona or contact BF Insurance Agency.
For more information, see our article on independent insurance agents.
Frequently Asked Questions
What is the difference between an insurance carrier and an insurance broker?
An insurance carrier is the company that underwrites and pays claims on your policy. A broker is an intermediary who may help you consider insurance options. A direct carrier offers its own products.
Do insurance brokers charge customers a fee in Arizona?
Ask whether any fee applies and how the broker is paid before sharing personal information or authorizing a policy.
Can an insurance broker help bundle home and auto insurance?
Bundling home and auto insurance may affect the total premium. Ask for the bundled and separate-policy costs so you can compare them.
Who helps with claims: an insurance broker or the carrier?
Claims handling and any assistance available depend on the policy and the parties involved. Ask what support is available if you need to make a claim.
Does buying insurance directly from a carrier cost less?
The cost depends on the policy and coverage selected. Compare the total cost, deductibles, and coverage limits rather than assuming one channel is cheaper.
The real challenge is not choosing between a broker and a direct carrier. It is knowing which one fits your coverage, your county, and your family's plans. BF Insurance Agency exists to answer that question with tailored Arizona coverage, bundled home and auto solutions, and guidance that continues after the policy is signed. Get started with BF Insurance Agency and get a quote you can actually compare.