 how-to
Finding Insurance for Non Standard Drivers: 2026 Guide
Table of Contents
- What Counts as a Non-Standard Driver
- How Insurers Assess Risk Before They Quote You
- State Minimum Liability Requirements You Still Have to Meet
- The SR-22 Insurance Filing Process, Step by Step
- Where to Find Carriers That Write Non-Standard Policies
- How to Lower Premiums for High-Risk Drivers
- How to Compare Quotes and Bind a Policy
- Frequently Asked Questions
Last Updated: October 7, 2026
What Counts as a Non-Standard Driver
Finding insurance for non standard drivers starts with one question: why did a standard carrier turn you down? A non-standard driver is someone whose driving record, insurance history, or vehicle falls outside the rules most major insurers use to decide who they will cover. The good news is that being turned down is a category, not a dead end.
Three things usually trigger it:
- At-fault accidents. One serious crash or a pattern of smaller ones.
- Traffic violations. Tickets, reckless driving, or a DUI.
- Coverage lapses. Even a short gap in your insurance history.
Here's what most people get wrong: they assume a rejection means no one will cover them. In reality, the standard market and the non-standard market are two different systems, and the second one exists precisely for drivers like you.
How Insurers Assess Risk Before They Quote You
Carriers run a risk assessment before you ever see a price. They pull your motor vehicle record, your claims history, and your prior insurance history, then sort you into a tier: preferred, standard, or non-standard.
What matters most is the pattern, not the single event. A DUI from years ago with a clean record since reads very differently than three tickets in the past year. Underwriting looks at how recent and how severe your issues are, plus how long you have held continuous coverage.
One insider tip: gaps in coverage hurt more than people expect. Carriers view a lapse as a sign you may drop coverage again, so keeping a policy active, even a basic one, protects your eligibility over time.
State Minimum Liability Requirements You Still Have to Meet
Non-standard status never removes the legal floor. Every state sets minimum liability coverage, and you must carry at least that much no matter which carrier writes your policy.
The official state insurance department guidance is the place to confirm your exact limits, because they vary by state. Typical minimums cover a set amount per person for bodily injury, a total per accident, and a figure for property damage.
Two things to keep straight:
- Minimum coverage satisfies the law but pays little if you cause a serious crash.
- Full coverage adds collision and comprehensive, which financed or leased cars usually require.
If you have a loan or lease, the lender's rules sit on top of the state's. Meet both.
The SR-22 Insurance Filing Process, Step by Step
An SR-22 is not a type of insurance and it does not change your coverage. It is a certificate your carrier files with the state motor vehicle agency to prove you are carrying the liability limits the state requires. Courts and licensing agencies order it after certain violations, most commonly a DUI, driving without insurance, an at-fault accident while uninsured, or repeated tickets. Until the filing period ends, your registration or license may stay suspended without it.
Here is the sequence most states follow:
- Confirm the requirement in writing. Your court paperwork, suspension notice, or state motor vehicle agency letter will state the required limits and the length of the filing period. Do not rely on a phone representative's summary.
- Find a carrier that files SR-22s in your state. Not every insurer does, and some that write non-standard policies still decline SR-22 filings. Ask directly: "Do you file the SR-22 with my state, and is there a filing fee?"
- Buy a policy that meets the required limits. The SR-22 does not set the limits, your state does. If your policy lapses below those limits, the carrier must notify the state.
- The carrier files the form with the state on your behalf, usually electronically. Confirm the state has received it before you drive.
- Keep coverage active for the entire filing period. This is the part that trips people up. A lapse, even a single day, triggers a new state notification, and most states restart the clock or extend the requirement.
- Verify the end date with the state, not just the carrier. Filing periods are commonly set at one to three years depending on the violation and state, but the exact term is state-specific.
Two mechanics worth understanding before you shop:
- Non-owner SR-22. If you do not own a car but need to file, often to reinstate a license, a non-owner policy can satisfy the requirement. It covers you when you drive a vehicle you do not own, but it does not cover the vehicle itself.
- Owner SR-22. If you own or are buying a car, you need a standard owner policy with the SR-22 attached. The filing rides on top of the policy.
Because filing fees, required limits, and filing periods vary by state, confirm the current rules through your state insurance department or motor vehicle agency before you bind. A carrier that files in one state may not file in another, so the question is always state-specific.
Where to Find Carriers That Write Non-Standard Policies
Specialty insurers and independent agents are the two main routes, and they solve the problem differently. A specialty insurer focuses on higher-risk drivers by design. An independent agent, by contrast, can shop your file across many carriers at once. (Source: National Highway Traffic Safety Administration (NHTSA) data)
Specialty Insurers vs. Independent Agents
| Route | Best For | Trade-Off |
|---|---|---|
| Specialty insurer | A single serious issue like a DUI | Narrower coverage choices |
| Independent agent | Comparing many carriers fast | You rely on the agent's panel |
| Direct online carrier | Simple, clean records | Often declines non-standard files |
We work as an independent agency, so we can match your specific history to carriers that accept it instead of pushing one company's product.
How to Lower Premiums for High-Risk Drivers
There is no magic switch, but there are real levers. Learning how to lower premiums for high-risk drivers comes down to reducing the risk the carrier sees.
- Raise your deductible. A higher deductible lowers your premium.
- Ask about discounts. Safe-driving programs, paid-in-full, and bundling all help.
- Improve your record. Time and clean driving lower your tier.
- Choose a payment plan that avoids installment fees.
- Re-shop every renewal. Your rate should improve as your record ages.
How to Compare Quotes and Bind a Policy
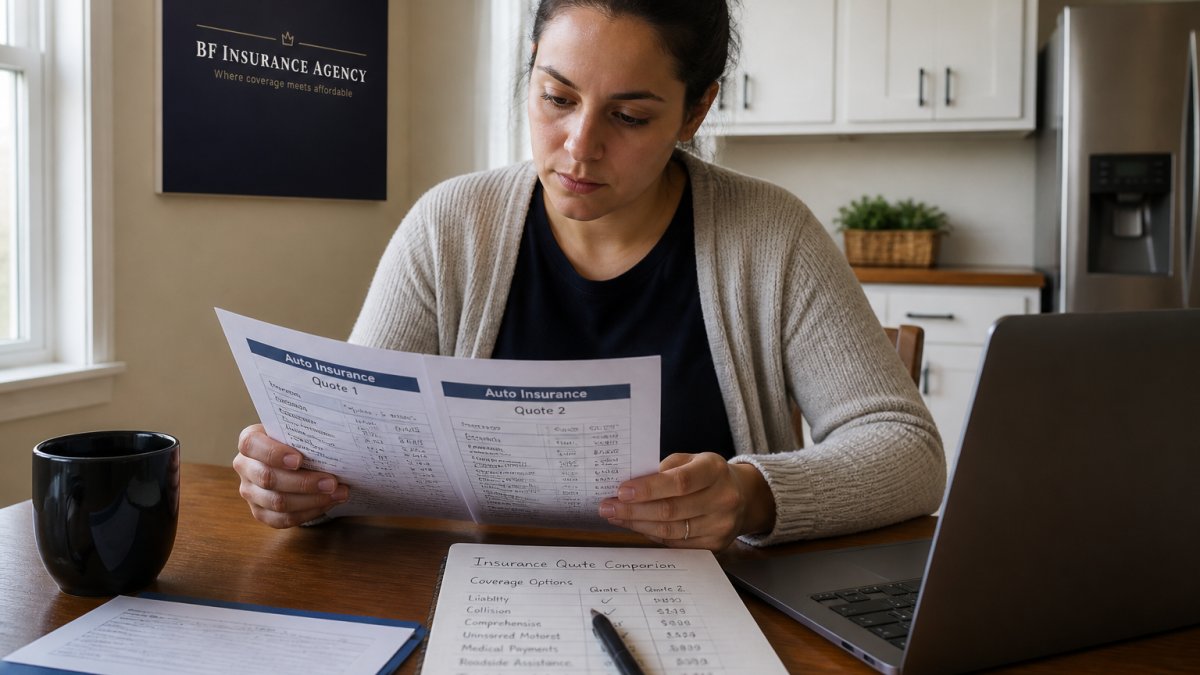
Most quote comparisons fail because the shopper compares premium to premium. Two policies with the same monthly price can pay out very differently after a claim. The right comparison is coverage-to-coverage, then price.
Build a like-for-like comparison
Before you request quotes, write down the coverage you want so every carrier is quoting the same thing:
- Bodily injury liability, per person and per accident limits.
- Property damage liability, a single limit.
- Uninsured/underinsured motorist, if your state offers it.
- Collision and comprehensive, with a stated deductible for each.
- Medical payments or personal injury protection, if required or desired.
- Rental reimbursement and towing, optional, but easy to overlook.
If a quote comes back without one of these, ask for it added before you compare prices. A missing coverage line is the most common reason a "cheaper" quote is not actually cheaper.
Evaluate policy quality, not just price
Four levers change what a policy actually pays:
- Deductibles. Raising a deductible lowers premium, but you pay that amount out of pocket on every covered claim. Match the deductible to what you could actually pay after an accident.
- Limits. State minimums satisfy the law but rarely cover a serious injury. If you have assets or income to protect, higher liability limits are usually worth the added premium.
- Exclusions. Read the exclusions page. Common ones include intentional acts, racing, using the vehicle for business, and named-driver exclusions. A named-driver exclusion means the policy will not pay if that person is driving.
- Fees and payment terms. Installment fees, reinstatement fees, and non-sufficient-funds charges vary by carrier. Ask for the total annual cost, not the monthly figure.
Bind the policy in the right order
- Gather your documents. Driver's license, vehicle title or registration, VIN, and proof of prior insurance if you have it.
- Get at least three quotes with identical limits and deductibles.
- Check the carrier's financial strength through a rating service so you know it can pay claims.
- Confirm the effective date and time. Coverage does not begin until the effective date on the policy, not when you pay.
- Pay the first premium and get confirmation in writing. Ask for the declarations page, ID cards, and, if applicable, confirmation that any required filing was submitted.
- Save the paperwork and note the renewal date. Continuous coverage is the fastest path back toward standard rates.
Once you bind, keep proof of insurance in the vehicle and a copy of the declarations page where you can find it. If you are filing an SR-22 or need same-day proof, confirm with the carrier that the state has received the filing before you rely on it.
Frequently Asked Questions
What defines a non-standard driver in the insurance industry?
A non-standard driver is someone an insurer places outside its preferred risk tier, usually because of an at-fault accident, a DUI, multiple traffic violations, a coverage lapse, or a thin insurance history. Carriers run their own underwriting, so the same driver can land in a standard tier with one company and a non-standard tier with another. That is why comparing quotes from several providers matters more for non-standard drivers than for anyone else.
How long does a high-risk status typically affect my insurance premiums?
It depends on the violation and the carrier's underwriting rules. Many insurers weigh accidents and tickets for roughly three years, while a DUI or an SR-22 requirement often stays on your record longer. Rather than guess, ask each carrier how long it applies its surcharge, then re-shop your policy when that window closes. Improving your driving record over time is the most reliable way to move back toward standard rates.
Can I get coverage if I have multiple traffic violations?
Yes. Specialty insurers and independent agents who work with high-risk drivers write policies for applicants with several violations, though you will pay more and may face higher deductibles or a larger down payment. Start by gathering your driving record and any SR-22 paperwork, then get quotes from at least three carriers. Check that each quote meets your state minimum liability requirements before you compare the premiums.
What is the difference between standard and non-standard insurance carriers?
Standard carriers target drivers with clean records and price accordingly. Non-standard or specialty insurers focus on higher-risk drivers, so they build their underwriting around accidents, violations, and lapses. A non-standard policy usually costs more and may carry tighter policy limits or payment terms. The trade-off is access: without these carriers, many high-risk drivers could not get proof of insurance at all.